Protect Your Assets: Smart Guide to Handling Home Loss Claims Now!

Introduction
Unexpected loss to a home, business, or rental space can create emotional stress and serious financial pressure. A leaking roof, burst pipe, fire, storm, or accident may seem like a temporary inconvenience at first, but the costs often rise quickly if the issue is not handled properly. That is why understanding how to respond, document losses, and protect your investment is essential.
Many people only think about insurance after something goes wrong. Others assume repairs are simple and can wait until later. In reality, delayed action often leads to higher expenses, hidden structural problems, and disputes over responsibility. Whether you own a house, rent an apartment, manage commercial property, or oversee multiple units, knowing the right steps can save you money and reduce stress.
This in-depth guide explains the most common causes of property damage, how insurance claims usually work, smart repair strategies, ways to prevent future issues, and practical advice for protecting your long-term financial stability. The goal is to help you make informed decisions with confidence.
Fast response, clear records, and quality repairs are the three pillars of successful recovery.
What Is Property Damage and Why Does It Matter?
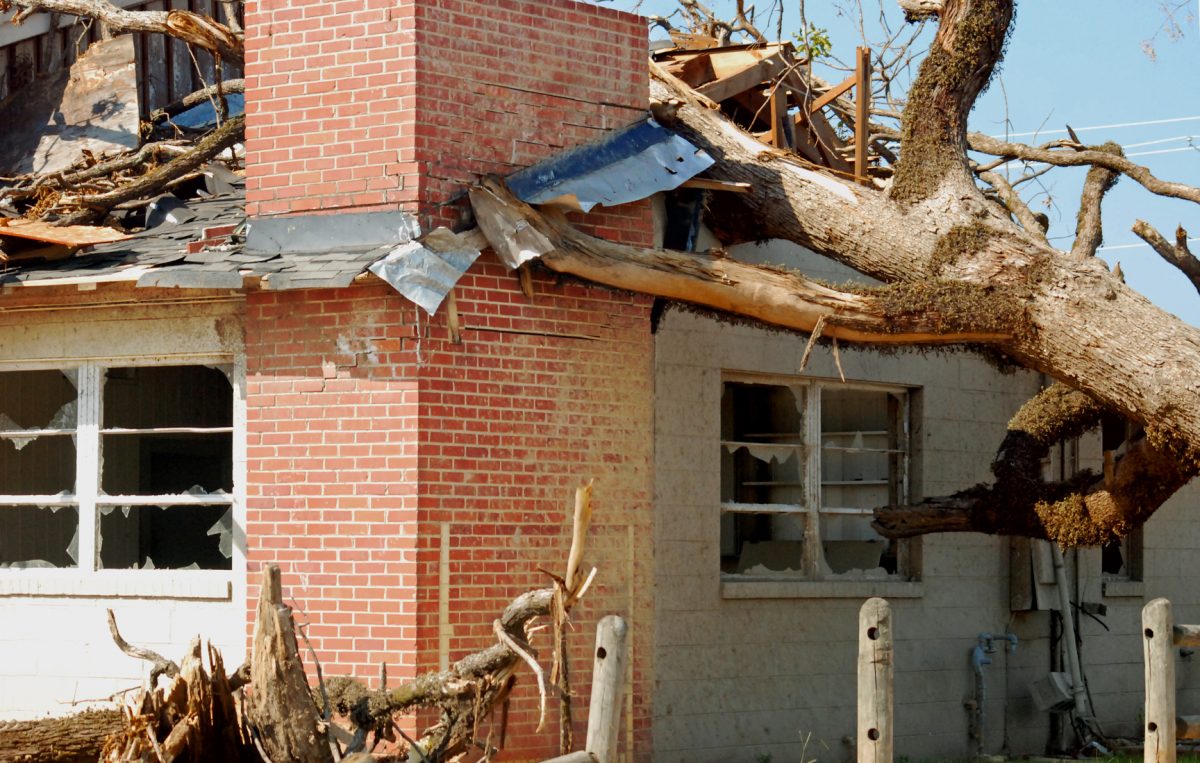
The term property damage refers to physical harm or destruction affecting buildings, land improvements, or personal belongings. It can range from minor cosmetic issues such as cracked drywall or broken windows to severe structural problems caused by fire, flooding, or storms.
This type of loss matters because property is often one of the most valuable assets a person or business owns. A damaged roof, foundation issue, or major water leak can reduce market value, interrupt normal life, and create safety hazards. Even small problems may become expensive if ignored.
For homeowners, damage can affect comfort, resale value, and savings. For landlords, it may create vacancy periods or disputes with tenants. For businesses, it can mean closure, lost income, and operational delays. In every case, proper handling is critical.
Common Causes of Damage to Homes and Buildings
Many people imagine dramatic disasters when they think of loss, but the most expensive incidents often begin with routine problems. Understanding common causes helps owners act early.
Water Intrusion
Water is one of the leading causes of expensive repairs. Burst pipes, leaking appliances, overflowing sinks, clogged drains, and roof leaks can spread moisture into walls, floors, and ceilings. Because water often travels unseen, damage may be worse than it first appears.
Fire and Smoke
Even a small kitchen fire can leave soot, smoke odor, and hidden wiring concerns. Flames may be extinguished quickly, but cleanup and restoration often take longer than expected.
Storms and Weather
Strong wind, hail, heavy rain, lightning, heat, and falling trees can affect roofing, siding, fencing, windows, and outdoor systems. Weather events are especially damaging when maintenance was already overdue.
Human Error
Unattended cooking, overloaded electrical outlets, careless drilling into pipes, and improper DIY repairs are frequent sources of preventable property damage.
Theft and Vandalism
Forced entry can destroy locks, doors, windows, alarms, and fencing. Graffiti and intentional destruction also require cleanup and repair.
Wear and Tear
Older plumbing lines, worn roofing materials, deteriorated sealants, and outdated electrical systems may fail unexpectedly if not inspected regularly.
The Financial Impact of Delayed Action
Many owners delay repairs because they hope the issue is minor or because they worry about costs. Unfortunately, waiting often creates larger bills.
A slow leak may turn into warped flooring, mold growth, ruined cabinets, and damaged wiring. A missing roof shingle can lead to attic moisture and insulation failure. A cracked window may invite water intrusion or security risks.
The true cost of delay includes more than labor and materials. It may also include:
- Temporary housing expenses
- Lost rental income
- Business interruption
- Higher insurance deductibles
- Mold remediation
- Reduced resale value
- Safety risks to occupants
When property damage occurs, prompt mitigation is usually the most cost-effective decision.
What to Do Immediately After Damage Happens
The first few hours are important. A calm and organized response can protect safety while preserving evidence for claims or reimbursement.
Prioritize Safety
If there is fire, exposed wiring, gas odor, unstable ceilings, or contaminated water, leave the area and contact emergency services or qualified professionals.
Stop Further Loss
If safe, shut off the water valve, cover a broken window, place buckets under leaks, or move valuables to a dry location. Temporary action can prevent worsening conditions.
Document Everything
Take wide-angle and close-up photos before cleanup begins. Record the date, time, and visible conditions. Video can also be helpful.
Notify Relevant Parties
Depending on the situation, contact your insurer, landlord, tenant, building manager, or contractor promptly.
Keep All Receipts
Emergency tarps, hotel stays, cleanup supplies, locksmith services, and temporary repairs may be important later.
This early phase often determines how smoothly recovery progresses.
How Insurance Usually Handles Losses
Insurance is designed to reduce financial shock, but coverage depends on policy language. Not all losses are treated equally.
Events Often Covered
Many policies may cover sudden incidents such as:
- Fire
- Windstorm damage
- Burst pipes
- Theft
- Accidental internal water release
Common Exclusions
Some policies may limit or exclude:
- Neglect or poor maintenance
- Gradual deterioration
- Flooding without separate flood coverage
- Pest infestation
- Earth movement in some regions
Deductibles Matter
Your deductible is the amount you pay before insurance contributes. Small claims may not exceed that threshold.
Actual Cash Value vs Replacement Cost
Actual cash value may deduct depreciation based on age and wear. Replacement cost often provides funds for new equivalent items, subject to policy terms.
Reading your policy before an emergency is one of the smartest financial habits you can develop.
The Claim Process Explained Step by Step
Filing a claim can feel overwhelming, especially during stressful circumstances. A structured approach helps.
Step 1: Report Quickly
Most insurers expect timely notice. Delays can complicate the process.
Step 2: Receive a Claim Number
Keep this number in your records for all communication.
Step 3: Submit Evidence
Provide photos, lists of damaged items, receipts, and a timeline of events.
Step 4: Meet the Adjuster
An adjuster may inspect the site and evaluate the scope of loss.
Step 5: Review Estimates Carefully
Read line items, labor assumptions, and material allowances. Ask questions if anything seems unclear.
Step 6: Begin Approved Repairs
Use qualified professionals and maintain written documentation.
When property damage claims are handled with organized records, misunderstandings are often easier to resolve.
Choosing the Right Repair Strategy

The cheapest estimate is not always the best option. Poor workmanship can create repeat failures, void warranties, or lower property value.
| Repair Option | Cost Range | Best Use | Risk Level | Long-Term Value |
|---|---|---|---|---|
| DIY Temporary Fix | Low | Minor urgent issues | High | Low |
| Budget Contractor | Medium | Cosmetic repairs | Medium | Medium |
| Licensed Specialist | Higher | Plumbing, roofing, electrical | Low | High |
| Full Restoration Firm | Highest | Fire or major water events | Low | Very High |
Focus on quality, safety, and durability rather than price alone.
How to Select a Trustworthy Contractor
Repair decisions matter as much as the claim itself. Choose carefully.
Verify Licensing and Credentials
Use professionals legally qualified for the work required.
Confirm Insurance Coverage
Contractors should carry liability and worker protections where required.
Read Recent Reviews
Look for consistency in communication, cleanliness, timelines, and problem resolution.
Request Written Estimates
Quotes should clearly explain labor, materials, schedule, warranties, and payment structure.
Avoid Pressure Tactics
Be cautious with anyone demanding full payment upfront or pushing immediate signatures.
Good contractors educate clients and communicate clearly.
Rental Property and Tenant Situations
Damage in rental housing can create confusion because multiple parties are involved. Responsibility depends on local law, lease terms, and cause.
Landlords often handle structural repairs, plumbing systems, roofing, and habitability concerns. Tenants may be responsible for negligence, misuse, or failing to report worsening issues.
For example, if a tenant notices a leak and reports it immediately, responsibility may differ from a situation where the leak is ignored for months.
Move-in and move-out photo records are extremely valuable. They reduce disputes and clarify condition changes over time.
If property damage affects rental housing, written communication is always better than verbal-only discussions.
Commercial Buildings Face Higher Stakes
For businesses, damage is more than a repair issue. It can disrupt income and customer trust.
A restaurant with water intrusion may lose inventory. A retail store with broken glass may close temporarily. A warehouse with roof failure may face delayed shipments.
Commercial owners should think beyond repair bills and consider:
- Revenue interruption
- Payroll obligations
- Lease commitments
- Inventory loss
- Equipment downtime
- Customer safety
- Reputation damage
Prepared businesses maintain emergency contacts, backup vendors, and clear documentation systems.
Hidden Damage Many Owners Miss
Visible issues are only part of the picture. Some of the most expensive repairs begin behind walls or under floors.
Moisture Behind Surfaces
Dry paint does not always mean dry framing. Moisture meters may reveal hidden saturation.
Mold Growth
Even modest leaks can create unhealthy indoor conditions if left untreated.
Electrical Problems
Water or fire exposure may compromise outlets, wiring, or panels.
Insulation Loss
Wet insulation often loses performance and may need replacement.
Structural Weakness
Repeated moisture can weaken wood members or corrode metal supports.
After property damage, professional inspection can prevent unpleasant surprises later.
Preventive Maintenance Saves Money
Routine care costs far less than emergency restoration. Owners who maintain systems consistently usually face fewer major losses.
Monthly Tasks
Check under sinks, inspect appliance hoses, test smoke alarms, and clear drains.
Quarterly Tasks
Review caulking around windows, inspect gutters, test shutoff valves, and trim branches near the roof.
Yearly Tasks
Schedule roof inspection, HVAC servicing, plumbing review, and exterior walkthrough.
After Major Weather
Inspect shingles, fences, siding, and drainage flow immediately.
Small maintenance habits often prevent large repair invoices.
Technology That Reduces Risk
Modern devices make prevention easier than ever.
Leak Sensors
Placed near water heaters, washing machines, or sinks, these devices can alert you before flooding spreads.
Smart Thermostats
Useful for reducing frozen pipe risks during cold weather or overheating during hot seasons.
Security Cameras
Helpful for theft claims, contractor oversight, and liability concerns.
Connected Smoke Detectors
Mobile alerts can speed response when no one is home.
Digital Inventories
Cloud-based photo records of rooms, receipts, and valuables simplify claims.
Technology cannot prevent every event, but it can shorten response time significantly.
Mistakes That Cost Property Owners Money
Even intelligent owners sometimes make expensive errors during stressful moments.
Waiting Too Long to Report Issues
Late notice can weaken claims and increase repair costs.
Discarding Damaged Items Too Soon
Keep affected materials or belongings until advised otherwise.
Hiring Based Only on Lowest Price
Cheap repairs often become expensive second repairs.
Ignoring Water Because It “Looks Dry”
Moisture often hides in subfloors or wall cavities.
Poor Record Keeping
Missing receipts and undocumented conversations create avoidable disputes.
Outdated Insurance Limits
Inflation and renovations may leave owners underinsured.
When Legal Advice May Be Helpful
Most losses are resolved without lawsuits, but some situations justify professional legal guidance.
Examples include:
- Denied or severely delayed claims
- Neighbor disputes over trees or drainage
- Contractor fraud or abandonment
- Commercial lease disagreements
- Construction defect issues
Bring organized records: photos, contracts, estimates, emails, inspection reports, and payment receipts.
Clear documentation strengthens your position and helps professionals assess options quickly.
How Climate Trends Are Changing Risk
Weather patterns in many regions now bring stronger storms, heavier rainfall, longer heat waves, or changing soil conditions. These shifts can increase the likelihood of roof stress, drainage overload, foundation movement, and electrical surges.
Smart adaptation includes:
- Improved drainage systems
- Impact-resistant roofing materials
- Better attic ventilation
- Surge protection devices
- Moisture-resistant finishes
- Tree maintenance programs
Future-focused upgrades often cost less than repeated recovery work.
Building a Recovery Budget After Major Loss
Large repairs can strain savings, so a structured plan helps restore control.
Separate Urgent and Optional Work
Prioritize safety, weatherproofing, and structural integrity first.
Collect Multiple Estimates
Competitive pricing helps reveal realistic market cost.
Negotiate Payment Schedules
Many firms allow milestone-based billing.
Track Every Expense
Hotels, storage, transport, cleanup, and temporary housing costs add up quickly.
Preserve Cash Flow
Avoid draining emergency reserves unnecessarily if financing options are better.
Strong budgeting turns chaos into a manageable project.
Long-Term Value Protection
Protecting value is not only about fixing visible issues. It is about preserving confidence for future buyers, tenants, or investors.
Maintain a property file containing:
- Repair invoices
- Inspection reports
- Warranty documents
- Renovation permits
- Insurance updates
- Before-and-after photos
Well-documented maintenance history can improve resale confidence and reduce buyer concerns.
Frequently Asked Questions
How fast should I report damage?
As soon as possible. Quick reporting reduces complications and helps prevent worsening conditions.
Should I clean before taking photos?
No. Always document first, then begin safe cleanup.
Is mold always covered by insurance?
Not always. Coverage depends on cause and policy wording.
Can I choose my own contractor?
Often yes, though some insurers may recommend preferred vendors.
What if the estimate seems too low?
Request clarification, gather additional quotes, and ask for scope review.
How often should policies be reviewed?
At least annually or after renovations and major purchases.
Do tenants need renter insurance?
Yes, renter coverage can protect personal belongings and liability exposure.
What is the best prevention tool?
Routine inspections combined with leak detection devices are highly effective.
Summary
Best First Response to Property Loss
- Stay safe
- Stop further harm
- Photograph everything
- Notify relevant parties
- Save receipts
- Use qualified repair help
Most Overlooked Risk: Hidden moisture behind walls and floors.
Best Financial Habit: Review insurance coverage once every year.
Conclusion: Smart Preparation Creates Strong Recovery
Unexpected property damage can feel overwhelming, but the right response makes a major difference. Fast action, detailed documentation, informed insurance decisions, and quality repairs can protect both your finances and your peace of mind. Owners who invest in regular maintenance, updated coverage, and reliable records are far better prepared when problems arise.
Do not wait for an emergency to think about protection. Inspect your property, review your insurance, build a contractor contact list, and store important records today. Preparation is the most affordable repair strategy you will ever make.
Read More:-Shield Your Assets With Smart Property Coverage That Truly Works


